

Last updated: 10 November 2026
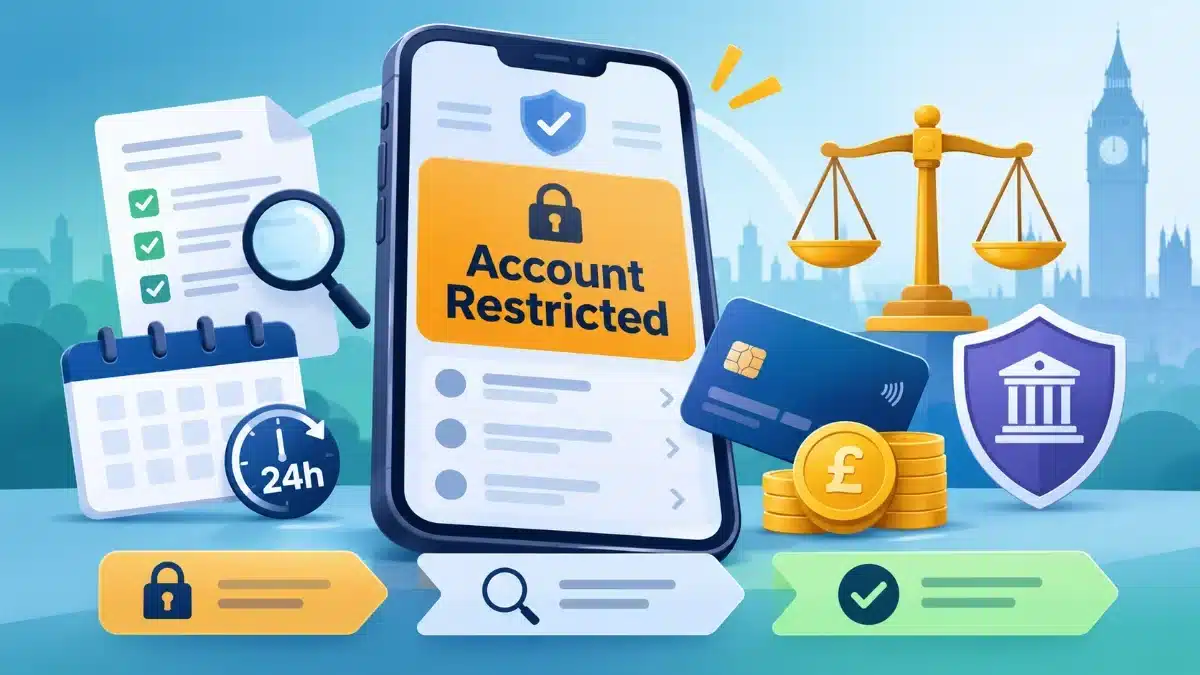
If your Zopa Biscuit current account has been restricted, you will usually see a banner in the app and find you can’t send money, receive money or manage your card. Zopa’s help page says it can’t confirm the exact reason.
That silence is allowed, within limits. This guide sets out what Zopa’s account terms say it can do, how a restriction differs from a closure under the debanking rules that started on 28 April 2026, what to do while you wait, and what the Financial Ombudsman has said about Zopa restrictions.
Table of Contents
In brief
- A restriction is a temporary block while Zopa reviews the account. It is not a closure.
- Zopa’s terms let it limit or suspend an account for security, suspected fraud, payments outside its “risk appetite”, a serious breach of the terms, or a legal or regulatory duty.
- Zopa says it will try to tell you before it acts and, where the law allows, give you the reason. Where money laundering or fraud checks are involved, the law can stop it saying anything.
- If Zopa asks for documents, it says it will review them and update you within 24 hours.
- The new 90-day notice and reasons rule covers closures of accounts opened on or after 28 April 2026, not temporary restrictions.
Why people are searching for this now
On 4 November 2026 a Zopa customer posted on the MoneySavingExpert forum that they had paid £20,000 into their Biscuit account to fund a fixed rate savings pot, only for the account to be restricted with two days left to fund it. The restriction lifted the same day without any documents being requested.
That pattern, a large deposit followed by a review, is a common trigger. Zopa’s own help page, Trustpilot reviews and two Financial Ombudsman decisions are the main results for “zopa account restricted” on Google UK. None of them puts the terms, the limits and your rights in one place.
What a restriction means on a Biscuit account
Zopa’s help page says that while the account is restricted you may not be able to make payments out, pay money in, or manage your debit card in the app, and that other app features will be limited.
Your money stays in the account. Zopa Bank Limited is authorised by the Prudential Regulation Authority and regulated by the FCA and the PRA, so deposits are covered by the FSCS up to £120,000 per person across all Zopa accounts.
What Zopa’s terms allow
Section 7 of the Zopa account terms (updated 28 April 2026) lets Zopa limit or suspend your account for any of these reasons:
- to protect the security of the account
- if it is worried about unauthorised or fraudulent use
- if your payments are outside its risk appetite (the terms give excessive spending on crypto or gambling as examples)
- if you have broken the terms in a serious way
- if letting you use the account could break a law, regulation or code, or expose Zopa to action from a regulator or law enforcement
- if the law requires it
- if you abuse or threaten its staff
The same section says Zopa will try to tell you before it acts. If that isn’t practical and the law allows, it will tell you straight afterwards and give you the reason. It will lift the restriction once the reason has been resolved.
One line matters if you have bills due: Zopa says it is not responsible for any money you lose because it stopped the use of your account in this way.
Why Zopa often won’t say why
The “where permitted by law” wording is the key. If a bank suspects money laundering, the Proceeds of Crime Act makes it an offence to tip off the customer in a way that could prejudice an investigation. So a bank may be legally unable to explain a review, even to a customer who has done nothing wrong.
That is why Zopa’s help page gives the same answer to everyone. It does not mean you are suspected of anything; checks on large or unusual payments are routine.
Restriction or closure? The 28 April 2026 rules
The Payment Services and Payment Accounts (Contract Termination) (Amendment) Regulations 2025 came into force on 28 April 2026. They changed what a bank must do when it closes an account, not when it restricts one.
| Situation | What applies |
|---|---|
| Account restricted while Zopa reviews it | Zopa’s terms, section 7. No set time limit. Reason given where the law allows. |
| Zopa closes an account opened on or after 28 April 2026, for an ordinary reason | At least 90 days’ notice and a reason detailed enough to understand, plus how to complain to Zopa and to the Financial Ombudsman |
| Zopa closes an account opened before 28 April 2026, for an ordinary reason | The law requires at least two months’ notice. Zopa’s current terms promise 90 days and a reason |
| Zopa closes an account over suspected fraud, financial crime or a legal duty | Zopa’s terms allow immediate closure without notice or a reason. The regulations include exceptions for money laundering and similar requirements |
So if your account is restricted rather than closed, the 90-day rule doesn’t apply yet. If a restriction turns into a closure, check which category the letter or email falls into.
Zopa’s payment limits: a check before you move large sums
Some people mistake a limit for a restriction. Zopa’s help page lists these limits on Biscuit accounts, which it says can’t be changed:
| Limit | Amount |
|---|---|
| Spending, rolling 24 hours (excluding Direct Debits) | £10,000 |
| Spending, rolling 7 days (excluding Direct Debits) | £30,000 |
| Transfers with linked bank accounts, rolling 24 hours | £250,000 |
| Cash withdrawals, rolling 24 hours | £400 |
| Gambling transactions, rolling 24 hours | £500 |
| Payments to crypto sort codes | £150 a day, £3,000 a month |
Rolling limits reset 24 hours (or 7 days) after each transaction, not at midnight. If a payment fails and the app shows no restriction banner, a limit is the more likely cause.
What to do if your Zopa account is restricted
- Check the app and your email. Zopa’s restricted account help page says it may need extra information. If it does, a banner appears on the app’s home screen; tap it to upload documents.
- Send what is asked for, once and in full. For a large deposit that usually means evidence of where the money came from, such as a statement from the sending account, a sale completion statement or a payslip. Zopa says it reviews documents and updates you within 24 hours of receiving them.
- Log in again later. In the 4 November MSE case, the restriction lifted on its own the same day.
- Tell Zopa about deadlines and hardship. If a fixed rate pot funding window, rent or a mortgage payment is at risk, say so. Zopa’s urgent support line runs 24/7 for issues that leave you vulnerable. It lists a restricted account among things best handled in the app.
- Move bills temporarily. If the review drags on, switch salary and Direct Debits to another account so essentials keep being paid.
- Keep a record. Note the date the restriction started, every message, and any cost it causes you (missed interest, late fees). You will need this if you complain.
Complaining, and what the Ombudsman has said
You can complain to Zopa by phone on 020 7580 6060 or by email to [email protected]. For complaints about payment services, the FCA’s rules give a firm 15 business days to send a final response, or up to 35 business days in exceptional cases if it explains the delay. If you don’t agree with the answer, or don’t get one in time, you can take it to the Financial Ombudsman Service for free.
Two published decisions about Zopa show where the line sits:
- DRN-6465384 (not upheld): a customer complained that Zopa restricted access to funds while it reviewed her account after a large deposit, and that its withdrawal limits weren’t clear. The ombudsman found that restricting an account during checks is not in itself wrong, that Zopa acted in line with its terms and gave reasons promptly, and that the review took no longer than reasonably needed. The limits were adequately disclosed.
- DRN-4280325 (upheld, £300): a customer’s credit card was blocked for about three weeks after Zopa wrongly changed her email address to someone else’s. The ombudsman said the block was too long, wasn’t explained to her, and was caused by Zopa’s own error. Zopa was told to pay £300 for distress and inconvenience.
The difference is useful. A complaint is stronger when the review drags on with no contact, when the bank caused the problem, or when you can show clear costs. It is weaker when the bank acted quickly and within its terms.
Verdict
A Biscuit account restriction is usually a short, routine check, often triggered by a large or unusual payment. Zopa’s terms give it wide powers to restrict and limited duties to explain. The new 90-day rule only protects you if the restriction becomes a closure.
The practical steps are the same each time: answer any request from Zopa quickly, protect your bills, and keep a record. If you plan to move a large sum into a fixed rate pot, fund it early rather than on the last day, so a review doesn’t cost you the rate.
For more on UK savings and account changes, see our Chip Smart Cash ISA review, our guide to Charter Savings Bank’s new online services, and what happened to customers in the Revolut and Google Cloud outage.
FAQ
How long does a Zopa account restriction last?
Zopa doesn’t give a time limit. It says it will review the account and update you, and that it responds within 24 hours once it has any documents it asked for. Some restrictions lift the same day.
Will Zopa tell me why my account was restricted?
Not always. Its terms say it will give a reason where the law allows, but anti-money laundering law can prevent a bank from explaining.
Is my money safe while the account is restricted?
It stays in the account and remains covered by the FSCS up to £120,000 across all your Zopa deposits.
Does the 90-day notice rule apply to a restriction?
No. The rule from 28 April 2026 covers account closures, with full protection for accounts opened on or after that date.
Can I get compensation?
Only if Zopa got something wrong, for example an unexplained, overlong block or one caused by its own error. The Ombudsman awarded £300 in one such Zopa case and rejected another where Zopa acted quickly within its terms.
Sources: Zopa account terms (updated 28 April 2026); Zopa: Why is my account restricted?; Zopa: transaction limits; Zopa: urgent bank account support; SI 2025/688, Payment Services and Payment Accounts (Contract Termination) (Amendment) Regulations 2025; FCA Handbook DISP 1.6; Financial Ombudsman DRN-6465384; Financial Ombudsman DRN-4280325; MoneySavingExpert forum, 4 November 2026.


Recent Comments