

Last updated: 4 November 2026
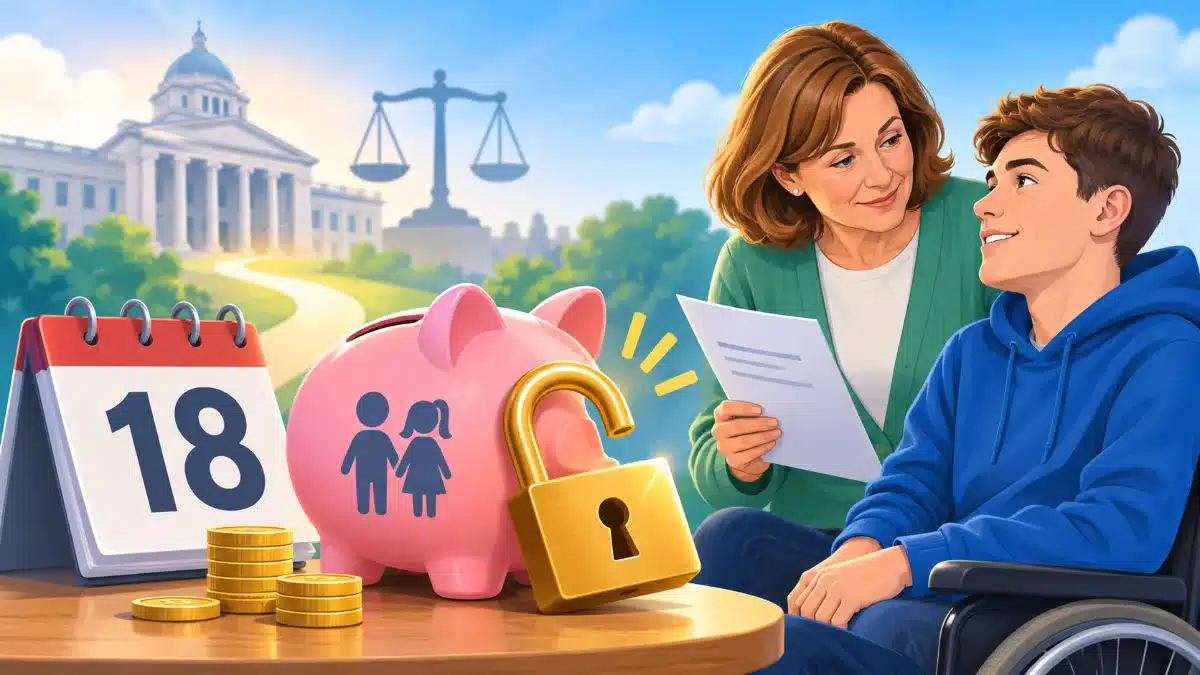
The Government says it will end the need for many families to go through the Court of Protection to reach a disabled young adult’s Child Trust Fund. What it hasn’t given is a start date, and nothing changes for families today.
The announcement on 3 November says parents and carers are expected to be able to go directly to providers. It puts the number affected at 63,000 to 126,000 young adults, and the average fund at £2,600.
Most reports we read stopped at the announcement. This guide covers the question that follows it: if your child’s fund is locked, or they turn 18 soon, what can you do before the law changes?
Table of Contents
The short version
- What’s promised: a simpler route through providers, set up by an amendment to the Financial Services and Markets Bill, with the detail in secondary legislation.
- What’s missing: a start date, who will qualify, what evidence you’ll need and what safeguards will apply. All are still to be worked out.
- What works today: a Court of Protection application, or a discretionary process that some providers already run.
- The date that matters now: your child’s 18th birthday, because the fee rules are more generous before it.
This is general information, not legal or financial advice. Your own circumstances, and your provider’s approach, will decide what fits.
Why these funds get locked
A Child Trust Fund is a tax-free account for children born between 1 September 2002 and 2 January 2011. The money belongs to the child, who can only take it out at 18.
On that birthday the young person automatically takes over the account. If they lack the mental capacity to manage it, gov.uk says a parent, close friend or relative needs to apply to the Court of Protection for a financial deputyship order.
Being a benefits appointee doesn’t solve this. Contact, the charity for families with disabled children, points out that the law only lets appointees manage benefit payments, not savings accounts.
Working from those birth dates, the oldest holders turned 18 on 1 September 2020 and the youngest will turn 18 on 2 January 2029. So some families have been waiting for six years, and anyone born after 4 November 2008 hasn’t reached 18 yet.
What the Government has actually committed to
The press release says new legislation will replace the Court of Protection process with a simpler route for Child Trust Funds. Campaigners, disability charities and the financial services sector will help decide who can access funds, what evidence is needed and what safeguards are proportionate.
The Court of Protection stays available as an alternative. The Bill itself began in the Lords in May 2026, so the amendment is being added to legislation already under way. The secondary legislation comes after that.
Contact says the law will use the industry process that campaigners developed with providers, and that this should make it quick to implement. That’s the charity’s expectation. The Government’s release gives no timetable.
Your options today
| Route | What it involves | Cost | Main catch |
|---|---|---|---|
| Ask the provider about its own process | Provider reviews evidence such as proof of incapacity and your role | No court fee | Discretionary, and not every provider offers it |
| Court of Protection, before 18 | Application for access to the fund | £432, often waived | Paperwork and waiting time |
| Court of Protection, after 18 | Same application, stricter fee position | £432, unless you qualify for help | Fee relief depends on your circumstances |
| Wait for the new law | No action now | Nothing | No date, and the rules aren’t written |
1. The provider process
Some providers will consider releasing money without a court order. Contact’s campaign page names OneFamily and Foresters Financial, and its June 2026 update adds Nationwide, Santander, Coventry and Co-operative Bank. The same update says HSBC doesn’t offer it.
This isn’t a legal right, and evidence requirements vary. OneFamily says it asks for a Court of Protection document first but will consider others.
In a Contact Q&A, Foresters listed evidence of DWP payments, medical evidence, a birth certificate, an indemnity form and bank details, and stressed that it differs case by case.
Don’t know who holds the account? HMRC’s free tool finds where it was opened, usually within three weeks online. It won’t tell you the balance, and you don’t need to pay a company to do this.
2. The Court of Protection
The current application fee is £432, plus £266 if the court holds a hearing and makes a final decision. Contact puts waiting times at around six months.
A full deputyship adds further costs: a £100 assessment fee for new deputies, then an annual supervision fee of £320, or £35 for minimal supervision, which applies to some property and affairs deputies managing less than £21,000. A security bond may also be required.
Whether you need a full deputyship or something narrower is a question for the court and your adviser. Solicitor Philip Warford said in the Contact Q&A that a one-off order might suit a small fund, with no guarantee the court will agree.
How the fees compare with a £2,600 fund
Here’s what the published fees would mean against the Government’s average balance, if no waiver applied. These are our sums, and they leave out any solicitor’s costs or bond.
| Scenario | Court and supervision fees | Share of £2,600 |
|---|---|---|
| Application only | £432 | 16.6% |
| Application plus hearing | £698 | 26.8% |
| Application, assessment, minimal supervision (first year) | £567 | 21.8% |
| Application, assessment, general supervision (first year) | £852 | 32.8% |
That’s why the fee rules below matter so much on a small fund. Supervision fees can also be reduced or waived if the person gets certain benefits or has an income under £12,000.
Why the 18th birthday still matters
The court’s guidance says you won’t pay the application fee if you apply only for Child Trust Fund access before the child’s 18th birthday and they have savings under £4,250 or monthly income under £1,420.
After 18, you may still avoid the fee through exceptional circumstances or the COP44A help with fees form, but it’s no longer the simple route.
So if your child is 16 or 17, it’s worth speaking to the provider now, even if you hope the new law will arrive first. Contact also advises approaching the provider before the 18th birthday. The Ministry of Justice’s toolkit for parents and carers covers England and Wales and explains how to prepare.
Should you apply now or wait?
Nobody can give you a reliable date, so it helps to ask what the delay would cost. These questions tend to decide it:
- Is the money needed soon? If it would pay for care, equipment or something else specific, an unknown wait has a real cost.
- Does the provider run its own process? One phone call answers this, and it costs nothing.
- Is the fee likely to be waived? A waived fee changes the sums in the table above.
- Do you need wider authority? The announcement concerns Child Trust Funds. If you also need to manage other money for your child, a deputyship may be needed anyway.
That last point is the one most likely to be lost in the headlines. From what’s been published, this is a fix for one type of account, not a general power to manage a young adult’s finances.
What’s still unclear
The numbers don’t match. The Government says 63,000 to 126,000 young adults. Contact estimates more than 80,000, locked out of £210 million. Using the Government’s £2,600 average, its range implies roughly £164 million to £328 million, though that’s our rough sum and the average may not hold for this group.
Junior ISAs. The release only mentions Child Trust Funds. Children born after 2 January 2011 can’t have one, and Contact’s campaign had pushed for Junior ISAs to be included. If your child has a Junior ISA, or you’re thinking of transferring a Child Trust Fund into one, ask how that would be treated under the new scheme.
Scotland and Northern Ireland. The release doesn’t address either. Scotland has an Access to Funds Scheme and Northern Ireland has its Office of Care and Protection, so the current routes differ there.
Limits. No maximum amount has been announced. The Government’s 2021 plan for a small payments scheme had a £2,500 limit, and Contact has asked for at least £5,000 under its appointee proposal. Neither is the new rule.
Once the money is accessible
The fund doesn’t have to be spent. Gov.uk says it can be withdrawn or transferred to an adult ISA, and whoever manages it needs to act in the young person’s interests.
If you’re comparing homes for it, check the exit terms, as our review of Chip’s Smart Cash ISA shows they can cost real money. Our guide to how moving savings can affect FSCS cover is worth reading too.
Separately, if your family is saving towards a first home, the First Time Buyer ISA rules are changing as well.
FAQ
Can I access my disabled child’s Child Trust Fund without going to court now?
Possibly. Some providers run their own process, at their discretion. The new legal route announced on 3 November isn’t in force and has no start date.
How much does the Court of Protection charge?
The application fee is £432, plus £266 if a hearing is held and a final decision made. Deputies can also pay assessment and annual supervision fees. Fee help is available in some cases.
Is the fee waived if I apply before my child turns 18?
Usually, if you’re applying only for Child Trust Fund access and your child has savings under £4,250 or monthly income under £1,420, according to the court’s guidance.
Should I withdraw my application now the law is changing?
We can’t advise on individual cases. The Court of Protection will remain available, and there’s no date for the new route, so talk to your solicitor or Contact before stopping anything.
Does being a DWP appointee let me access the fund?
Not on its own. Appointees manage benefits, not savings accounts, although Foresters says being the appointee can help a case under its own process.
Who can help?
Contact offers advice on the industry process through its campaign page. Your provider can tell you what it will accept.
Sources: Ministry of Justice and HM Treasury, 3 Nov 2026; gov.uk Child Trust Funds; Court of Protection fees (COP44); gov.uk deputy fees; Contact, 3 Nov 2026.


Recent Comments