

Last updated: 30 October 2026
The government has confirmed that a new First Time Buyer ISA will replace the Lifetime ISA from April 2029. The final design, published by HM Treasury alongside the Budget on 28 October 2026, keeps the 25% bonus and the £450,000 price cap but drops the age limit and the withdrawal penalty.
A separate change is already in force. From 29 October 2026, Lifetime ISA savers who buy a first home above £450,000 pay a 20% withdrawal charge instead of 25%, so they get back what they paid in.
Most Budget coverage has focused on the cash ISA limit, which stays at £20,000. This piece sets out what the Treasury’s response document actually says, what it leaves open, and what LISA and Help to Buy ISA holders can do now.
Table of Contents
What the government has decided
The Treasury received 194 responses to its consultation, which ran from 22 June to 18 August 2026. Its response confirms the following design.
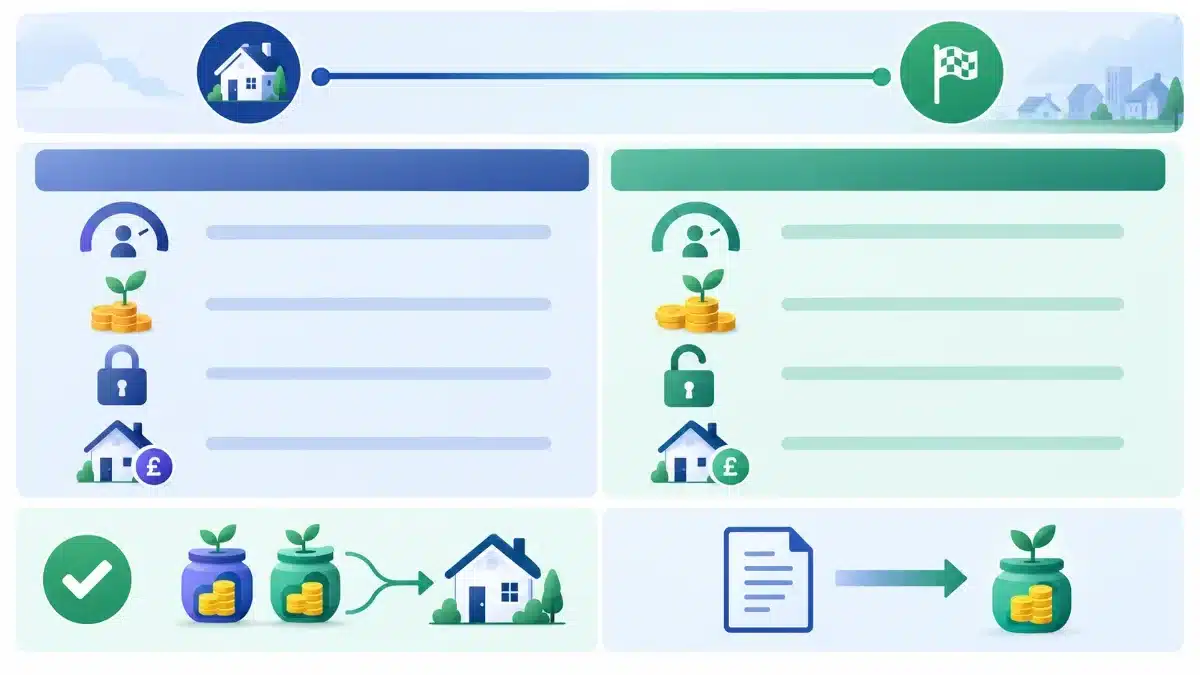
| Feature | First Time Buyer ISA (from April 2029) | Lifetime ISA (today) |
|---|---|---|
| Who can open | Anyone 18 or over, no upper age limit | Aged 18 to 39 |
| Annual limit | £4,000 (counts towards the £20,000 ISA allowance) | £4,000 (same) |
| Bonus | 25% of the final account balance, up to £20,000 | 25% of contributions, up to £1,000 a year |
| When the bonus is paid | At exchange of contracts | Monthly, into the account |
| Property price cap | £450,000 | £450,000 |
| Minimum holding period | 1 year | 12 months from first payment |
| Mortgage required | Yes | Yes |
| Withdrawal charge | None | 25% (20% for first homes above £450,000 from 29 Oct 2026) |
| Use for retirement | Not part of the published design | Yes, from age 60 |
| Account types | Cash and stocks and shares | Cash and stocks and shares |
Two design choices stand out. The bonus is worked out on the final balance, so investment growth earns the 25% too. And because there is no withdrawal charge, savers who change their plans can take their money out without losing part of their own contributions.
The Lifetime ISA change that started on 29 October
Until now, a LISA saver whose first home cost more than £450,000 paid the standard 25% charge. Because the charge applies to the whole pot, it took back the bonus and a slice of the saver’s own money as well.
From 29 October 2026, the charge for these purchases drops to 20%. HMRC says this lets savers “retain their own contributions while removing the government bonus.” The 25% charge still applies to every other unauthorised withdrawal.
| Example: £12,000 paid in, £3,000 bonus, home costs £475,000 | Before 29 Oct | From 29 Oct |
|---|---|---|
| Pot | £15,000 | £15,000 |
| Withdrawal charge | £3,750 (25%) | £3,000 (20%) |
| You receive | £11,250 | £12,000 |
| Own money lost | £750 | £0 |
One catch for stocks and shares LISAs: the 20% is charged on the whole pot, including growth. If the same pot had grown to £16,500, the charge would be £3,300 and you would keep £13,200. That is your £12,000 back plus £1,200 of the £1,500 growth.
How the new bonus compares
Say you pay in £4,000 a year for three years and the account is worth £13,000 when you exchange. The First Time Buyer ISA bonus would be 25% of £13,000, or £3,250.
A LISA with the same £12,000 of contributions earns a £3,000 bonus. That bonus arrives along the way and can grow too, so in a cash account the two end up close. The bigger differences are elsewhere: no age limit, no penalty for changing your mind, and a £20,000 bonus ceiling, which you would reach at a balance of £80,000.
The flip side is that the bonus only arrives at exchange, and the response says buyers will have 90 days from claiming it to complete. Anyone who exchanges and then sees the chain collapse will want the details of that rule before relying on it.
What this means if you already save
Lifetime ISA holders
Accounts opened before the switch “continue under existing terms,” according to the response. You cannot transfer a LISA into the new account, but you can use both towards the same purchase.
The design table also says subscriptions are allowed into one account per tax year, “including a LISA or FTB ISA”. In practice, from April 2029 you may have to choose which one to pay into each year.
Help to Buy ISA holders
You get a dedicated window. Between 6 April 2029 and 1 December 2030, you can move your full Help to Buy ISA balance into a First Time Buyer ISA without it counting towards the £4,000 limit. The Help to Buy ISA closes on 1 December 2030.
Over-40s who never opened a LISA
This is the group that gains most. If you are 40 or older and still saving for a first home, there is no product for you today. From April 2029 there will be, with no upper age limit.
What the government has not said yet
- When the Lifetime ISA stops taking new accounts or new payments
- Whether new LISA savers after 2029 lose the retirement option at 60
- Which banks and platforms will offer the account
- Exactly how the 90-day completion rule works if a purchase falls through
The Treasury says the detail will follow in legislation. Until then, nothing changes for LISA savers buying under the cap.
The Budget also confirmed the cash ISA limit stays at £20,000 and said the government will “explore a new ISA incentive” for first-time stocks and shares investors. If you hold cash inside a stocks and shares ISA, our guide to moving cash out before April 2027 covers the separate rules on transfers. For first-time investors weighing a platform offer, see our reviews of the J.P. Morgan Personal Investing £100 offer and the Scottish Widows app £25 share dealing offer.
FAQ
When does the First Time Buyer ISA launch?
April 2029, according to the government’s consultation response published on 28 October 2026.
Is the Lifetime ISA being scrapped?
The First Time Buyer ISA will be offered in place of the LISA from April 2029. Existing LISAs opened before then continue under their current terms.
Can I transfer my Lifetime ISA into the new account?
No. The government has ruled this out to avoid paying two bonuses on the same money, but you can use both accounts for the same home.
What is the new Lifetime ISA withdrawal charge for homes over £450,000?
20%, for first-home purchases above the cap made on or after 29 October 2026. Other unauthorised withdrawals still face 25%.
Is there an age limit on the First Time Buyer ISA?
You must be 18 or over to open one. There is no upper age limit.
Is the bonus paid on investment growth?
Yes. The 25% bonus is calculated on the final account balance, up to a maximum bonus of £20,000.
This article explains government policy and is not personal financial advice.
Sources: HM Treasury, First Time Buyer ISA consultation and government response (October 2026); HMRC, Lifetime ISA withdrawal charge (28 October 2026); HM Treasury, Budget 2026; GOV.UK, Lifetime ISA.


Recent Comments