

Last updated: 9 November 2026
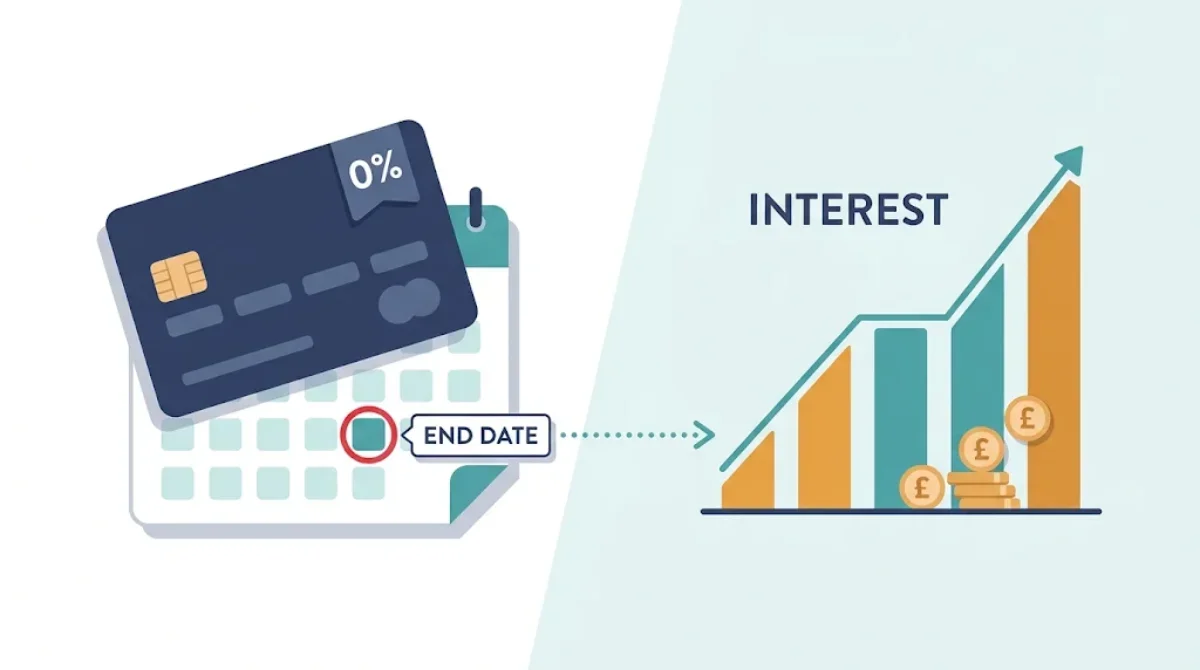
If you used the Chase credit card’s 0% purchase offer, the end date matters more than the payment date. Chase’s own terms mean interest can start on the leftover balance from the day the offer ends, even if your monthly repayment is set to pay in full.
A Chase customer raised exactly this on the MoneySavingExpert forum on 8 November. They had switched their regular repayment to the full balance as the offer ended, then found interest charged from the end date. This guide explains why, what it costs, and how to avoid it.
Table of Contents
The Chase credit card in brief
The card is only open to Chase current account customers, and you check eligibility in the Chase app. Chase’s product page lists these headline terms:
| Feature | What Chase says |
|---|---|
| Representative APR | 24.9% APR (variable), based on a £1,200 credit limit |
| Rate range | 24.9% to 29.9% APR, depending on your circumstances |
| Monthly purchase rate | 1.870% to 2.204% |
| 0% offer | 0% on purchases for up to 3 months, if you make your minimum payments |
| Interest-free days | Up to 56 days on purchases when you pay in full and on time |
| Cashback | 2% on everyday spending categories, up to £20 a month (Chase current and saver accounts required) |
| Fees | No monthly or annual fee; no foreign transaction fees; £12 late payment fee |
You apply through the Chase credit card page or the app. The “up to” matters: Chase’s credit agreement says your promotional rate and purchase period are “tailored to you”, so not everyone gets the full 3 months.
Why interest can start the day the 0% offer ends
Three clauses in Chase’s terms work together here.
1. The leftover balance moves to the standard rate
Chase’s credit card agreement says its standard interest rates apply “on any remaining balance after the end of a promotional offer period”. Whatever you still owe from the 0% period starts costing 24.9% to 29.9% APR from that point.
2. Interest-free days only cover new purchases
The interest-free period (up to 56 days) is the part most people rely on. But Chase’s Additional Terms say it only covers “purchases made during your latest statement period”, and only if you pay the full statement balance and the previous month’s balance in full by the due date.
Both conditions exclude balances on a 0% promotional rate. So the old 0% balance was never inside that grace period. Once its 0% ends, nothing stops interest building on it each day.
3. Trailing interest runs until the money arrives
Chase charges trailing interest “on your outstanding balance for the dates between your statement date and the date you pay off your balance”. It appears on your next statement, even if you don’t use the card again.
Put together: paying the statement in full clears the balance, but it doesn’t undo the interest that built up between the offer end date and the day your payment landed.
What it costs: worked examples
Chase calculates interest daily, using a simple annual rate on a 365-day year. At the 1.870% monthly rate, that’s about 0.0615% a day. These figures assume the balance doesn’t change and ignore any new spending.
| Balance left when the 0% ends | Days until your payment arrives | Interest at 24.9% APR | Interest at 29.9% APR |
|---|---|---|---|
| £500 | 30 | £9.22 | £10.87 |
| £900 | 10 | £5.53 | £6.52 |
| £900 | 25 | £13.83 | £16.30 |
| £1,200 | 25 | £18.44 | £21.74 |
That can wipe out a month or more of the card’s cashback. At the £20 monthly cap, a £1,200 balance left for 25 days at the top rate costs more than the best month’s reward.
Why “Pay in Full” on the 27th may be too late
Chase takes regular credit card repayments on the 27th of each month. You can choose the full statement balance, the minimum, or a fixed amount, and you must change it by the 26th.
Your 0% end date doesn’t line up with the 27th. If the offer ends on, say, the 5th, the leftover balance can build interest for about three weeks before the regular repayment goes out. Switching to full repayment changes what you pay on the 27th, not when interest starts.
How to avoid the charge
- Find your end date. In the Chase app, open the credit card, tap the three dots at the top right, then “See interest rate”. Your monthly statement also shows when the promo rate ends.
- Clear the 0% balance before that date. Make a one-off repayment from your Chase account a few days early, rather than waiting for the regular repayment on the 27th.
- Check the next statement. If a small trailing interest charge still appears, it relates to days before your payment landed. Ask Chase to explain any amount you can’t match to those dates.
- Never miss a minimum payment. Chase’s agreement says you lose promotional rates if it doesn’t receive the minimum payment on time, or if you go over your credit limit. A missed payment also costs £12.
Chase says it will tell you when promotional rates are about to end. Treat that message as your deadline to pay, not a reminder to change your repayment setting.
Is it Chase being unusual?
Trailing interest isn’t unique to Chase, so check your other cards’ terms for the same clause. What catches people out with Chase is the short offer of up to 3 months and the fixed repayment date on the 27th.
If you want a longer interest-free stretch for a large purchase, compare specialist 0% purchase cards. Our Zable credit card review shows how a different card’s fees and terms stack up. For cashback, see what changed with Lloyds Ultra cashback after the first year.
If you already hold Chase’s investing account, our piece on the J.P. Morgan Personal Investing £100 offer covers how those terms changed too.
Our verdict
The Chase credit card is a decent everyday card for Chase customers: no annual fee, no foreign fees and up to £20 a month in cashback. The 0% offer is short, though, and the terms give no grace period on what’s left when it ends.
The fix is simple. Note the end date in the app and clear the promotional balance before it, using a one-off payment. Don’t rely on the regular repayment on the 27th or the “pay in full” setting to do it for you.
FAQ
How long is the Chase credit card 0% offer?
Up to 3 months on purchases, as long as you make your minimum payments. Chase tailors the period to each customer, so check yours in the app.
How do I know when my Chase 0% period ends?
Open the credit card in the Chase app, tap the three dots at the top right, then “See interest rate”. The end date is also on your monthly statement.
Does Chase charge trailing interest?
Yes. Chase’s Additional Terms say it charges trailing interest on your outstanding balance between your statement date and the date you pay it off.
Why was I charged interest when I paid in full?
Interest-free days only cover new purchases from your latest statement, and exclude 0% balances. Once the offer ends, the leftover balance builds interest daily until your payment arrives.
Can I lose the 0% rate early?
Yes. Chase’s agreement says you lose promotional rates if it doesn’t receive your minimum payment on time or you go over your credit limit.
What is the Chase credit card’s APR?
The representative rate is 24.9% APR (variable), based on a £1,200 limit. Individual rates range from 24.9% to 29.9% APR.
This guide explains how Chase’s published terms work. It isn’t personal financial advice. If you’re struggling with card repayments, contact Chase or a free debt advice service.
Sources: Chase credit card product page; Chase Credit Card Agreement; Chase Credit Card Additional Terms; Chase Credit Summary Box; Chase: paying your credit card; Chase: managing your credit card; MoneySavingExpert forum, 8 November 2026. All checked 9 November 2026.


Recent Comments