

Last updated: 2 November 2026.
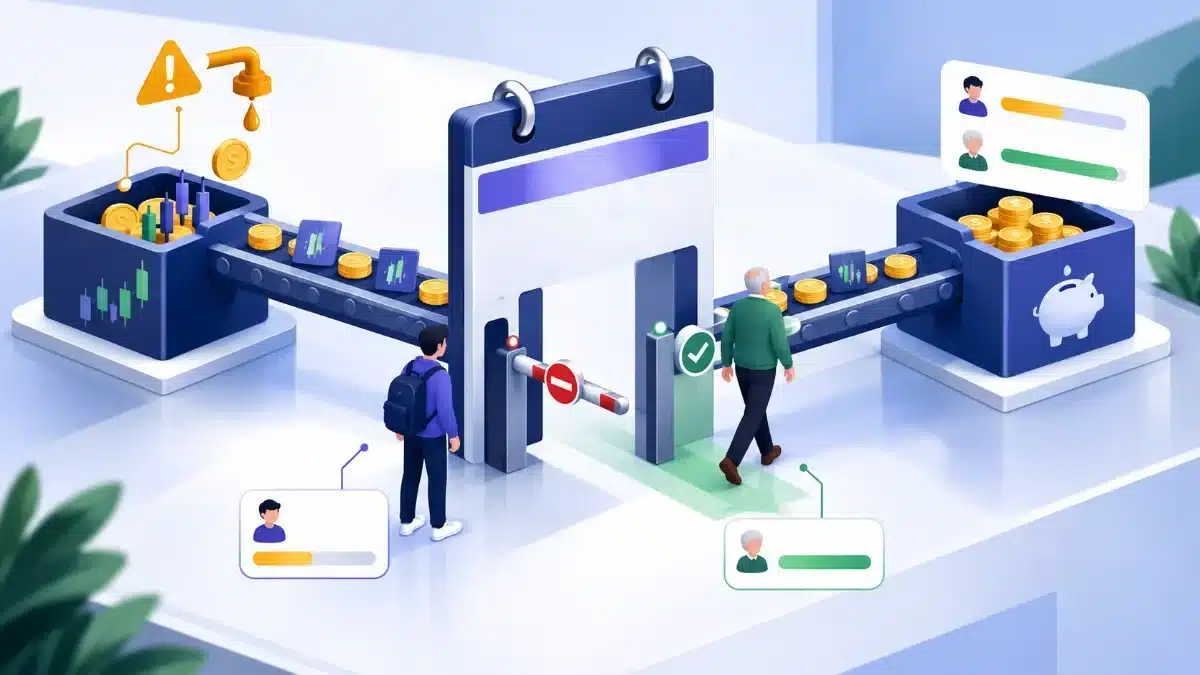
Correction (2 November 2026): We first published this article on 19 October 2026 to explain ISA rules due to start on 6 April 2027: a £12,000 cash ISA limit for under-65s, a ban on moving a stocks and shares ISA into a cash ISA, a 22% charge on cash interest inside stocks and shares ISAs, and a new test on money market funds. At the Budget on 28 October 2026, the government scrapped all of them. We have rewritten the article to reflect the rules as they now stand.
The annual cash ISA limit stays at £20,000 from 6 April 2027, for savers of all ages. HMRC confirmed on 29 October that the planned cut and its “associated anti-circumvention rules” will not take effect, and that the regulations that introduced the £12,000 limit will be revoked.
Table of Contents
What the Budget changed
| Rule from 6 April 2027 | Planned before the Budget | Now |
|---|---|---|
| Overall ISA allowance | £20,000 | £20,000 (unchanged) |
| Maximum paid into cash ISAs | £12,000 for under-65s; £20,000 for 65 and over | £20,000 at any age |
| Transfer from a stocks and shares or Innovative Finance ISA to a cash ISA | Not allowed for under-65s | Still allowed |
| Charge on interest from cash held in a stocks and shares ISA | 22%, all ages | No charge |
| Stocks and shares ISA invested only in money market funds | Would stop qualifying | No new test |
Sources: the Budget 2026 document (section 3.9) and HMRC’s tax-free savings newsletter 24 (29 October 2026).
The government also said it will work with the investment industry to explore a new ISA incentive for people investing in a stocks and shares ISA for the first time. No details have been published yet.
If you were planning a transfer before April 2027
There is no longer a deadline. Moving money from a stocks and shares ISA to a cash ISA stays allowed after 6 April 2027, whatever your age, so there is no need to rush a transfer to beat the old cut-off.
The normal transfer rules still apply. HMRC’s guidance for ISA managers sets a 15 business day limit for transfers from one cash ISA to another. Other transfers, including stocks and shares to cash, have no fixed HMRC deadline and follow the provider’s own terms. Investments have to be sold before the money can move, which adds settlement time.
Use the formal ISA transfer process. If you withdraw the money yourself and pay it into another ISA, it counts as a new subscription against that year’s allowance.
Cash inside a stocks and shares ISA
Interest on cash held inside a stocks and shares ISA stays tax-free. The 22% charge described in the first version of this article will not be introduced.
Outside an ISA, savings are about to be taxed more heavily. The technical note on savings tax rates from Budget 2025 raised the tax rates on savings income by two percentage points from April 2027. Budget 2026 adds a further two points from the same date, which takes them to 24% for basic-rate, 44% for higher-rate and 49% for additional-rate taxpayers.
Here is what that means for £800 of savings interest (£20,000 at 4%) in 2027/28, if all of it is taxable:
| Saver | Inside an ISA | Outside an ISA |
|---|---|---|
| Basic-rate taxpayer | £0 | £192 |
| Higher-rate taxpayer | £0 | £352 |
| Additional-rate taxpayer | £0 | £392 |
Interest rates vary between providers, and many platforms pay less than 4% on uninvested cash.
Money market funds
The planned test that would have stopped a stocks and shares ISA holding only money market funds was one of the anti-circumvention rules that HMRC says will not take effect. Nothing changes for money market funds held in a stocks and shares ISA.
The FSCS angle: platform cash vs a cash ISA
Where the cash sits still changes how it is protected. Cash held on an investment platform is client money, generally covered by the Financial Services Compensation Scheme up to £85,000 if the platform fails and money is missing. A cash ISA with a bank or building society is a deposit, covered up to £120,000 per person per banking licence.
We covered how platform failures play out in practice in our piece on Jarvis Investment Management’s special administration, where client accounts were frozen while the administrators reconciled holdings. And if you hold savings with banks that share a licence, the £120,000 limit is per licence, not per brand, as we explained in Halifax moving to Lloyds.
What to do now
This is general information, not personal advice.
| Situation | What it means now |
|---|---|
| Under 65 and saving more than £12,000 a year in cash | You can keep paying up to £20,000 a year into cash ISAs after April 2027 |
| Cash or money market funds in a stocks and shares ISA | No deadline to move it; transfer to a cash ISA whenever the rate suits you |
| Transfer already in progress | It completes under your provider’s normal terms |
| 65 or over | No change from the rules you have today |
FAQ
Is the cash ISA limit still being cut to £12,000?
No. The government confirmed at the Budget on 28 October 2026 that the cash ISA limit stays at £20,000 from 6 April 2027, for all ages.
Can I still transfer a stocks and shares ISA to a cash ISA after April 2027?
Yes. The planned ban for under-65s was scrapped along with the other anti-circumvention rules.
Will interest on cash in my stocks and shares ISA be charged at 22%?
No. That charge will not be introduced.
What happens to the regulations that set the £12,000 limit?
HMRC says the Individual Savings Account (Amendment) (No. 2) Regulations 2026 will be revoked.
Are taxes on savings changing?
Yes, outside ISAs. From April 2027 the rates on savings income rise to 24%, 44% and 49%, after increases announced at both Budget 2025 and Budget 2026.
Sources: HM Treasury, Budget 2026 (28 October 2026), section 3.9; HMRC, Tax-free savings newsletter 24 (29 October 2026); The Individual Savings Account (Amendment) (No. 2) Regulations 2026 (SI 2026/1018); HM Treasury/HMRC, Change to tax rates for property, savings and dividend income: technical note (26 November 2025); HMRC, Transfer an ISA if you’re an ISA manager; FSCS.


Recent Comments