

Last updated: 21 October 2026
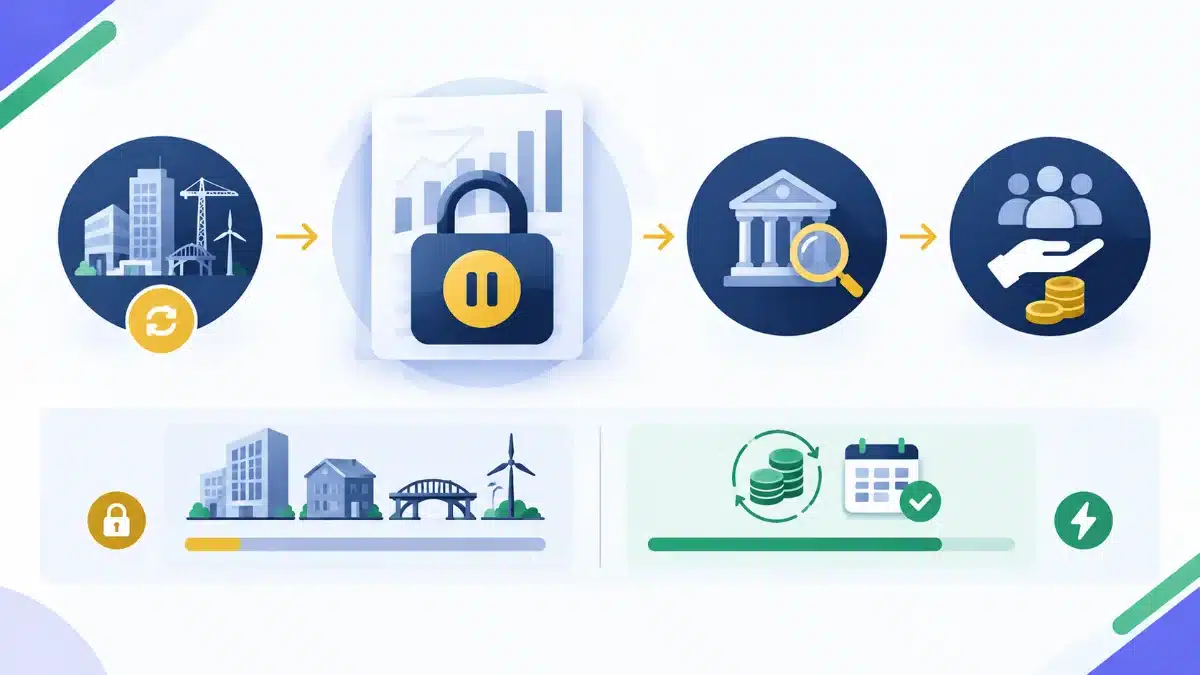
If you hold the St. James’s Place Diversified Assets fund, you can’t sell, switch or add to it. St. James’s Place (SJP) suspended dealing on 30 September 2026 and has asked the Financial Conduct Authority (FCA) for permission to close the fund altogether.
The fund was reported at about £1.4bn. SJP says it was less than 0.6% of the money it managed at the end of August. For the clients who hold it, that’s little comfort: their money is frozen until the FCA signs off and the remaining assets are sold.
Investors are now getting letters, and some are asking on forums whether they’ll get all their money back. This guide sets out what SJP has confirmed, what it hasn’t, and the questions worth putting to your adviser before the money moves.
Table of Contents
Contents
- What happened, and why
- The wind-up timeline
- What it means for you, by how you hold it
- Will you get all your money back?
- Charges during the suspension
- Why the FCA’s new fund proposals matter here
- Five questions to ask your SJP adviser
- Verdict
- FAQ
What happened, and why
The fund’s full name is the St. James’s Place Diversified Assets (FAIF) Unit Trust. FAIF stands for “fund of alternative investment funds”, a type of non-UCITS retail scheme that is allowed to hold harder-to-sell assets than an ordinary unit trust. KKR, the US private markets firm, is its investment adviser.
SJP gives three reasons in its client notice:
- demand had been falling for some time, with more money withdrawn than invested every year since 2023
- part of the fund (less than a quarter) was in private market assets, which take longer to sell than listed shares or bonds
- after a strategic review, SJP decided the fund “no longer has a long-term role” in its range
That combination is the classic problem for open-ended funds: investors expect to get their money out quickly, but some of what the fund owns can’t be sold quickly. Steady outflows force a manager to sell the easy-to-sell assets first, which leaves the remaining investors with a growing share of the hard-to-sell ones.
SJP moved before that became acute. On 29 September it accepted an offer for all of the fund’s private market holdings in one deal. It says the fund now holds only publicly traded bonds and cash. The suspension followed the next day.
SJP stresses that the decision “does not reflect a change” in its view of alternative investments as an asset class.
The wind-up timeline
SJP’s planned closure timeline gives steps rather than dates, and it says all timings are estimates.
| Step | What happens | Status or expected timing |
|---|---|---|
| 1. Suspension | No buying, selling or switching. Linked life and pension funds also stop trading | In place since 30 September 2026 |
| 2. Fund charge cut | Fund charge reduced to zero; KKR waives its fees | Done |
| 3. Private assets sold | Whole private market portfolio sold in one transaction | Offer accepted 29 September |
| 4. FCA application | SJP asks the FCA for approval to close the fund | Made; review “can take up to four weeks” |
| 5. FCA decision | If approved, SJP writes to investors and the fund enters its closing phase | Roughly late October to November, if the four-week estimate holds |
| 6. Wind-down | KKR sells the remaining bonds and cash holdings | “Days rather than weeks” after approval |
| 7. Money returned | Proceeds reinvested in your other SJP funds, or paid to a transaction account | SJP aims to return capital within 2026 |
| 8. Final closure | Legal wind-up completed | 2026 performance shown in the Annual Wealth Report in the new year |
If the FCA refuses, the fund stays suspended while SJP looks at other options. SJP calls that outcome unlikely. One investor on the MoneySavingExpert forum said their letter promised more information in November, which fits the timetable above.
What it means for you, by how you hold it
Many SJP clients don’t hold the unit trust directly. They hold it through an ISA, an investment bond or a pension, and SJP runs separate life and pension funds that invest 100% in the unit trust. Those are frozen too.
| How you hold it | What’s frozen | What to check |
|---|---|---|
| Unit trust, held directly | Selling, switching and new money | Whether proceeds will be reinvested or paid out, and any capital gains tax position on the disposal |
| Unit trust inside an SJP ISA | Selling, switching and new money in this fund | That proceeds stay inside the ISA wrapper, so they keep their tax-free status |
| Investment bond (unit-linked fund) | Transactions in the linked fund | Which fund the money moves into, and whether a switch inside the bond counts as a chargeable event |
| Pension (unit-linked fund) | Transactions in the linked fund | Where the money goes, and whether any planned withdrawals or transfers are held up |
SJP says you may get more than one letter if the fund sits in several of your products. It also says you don’t need to do anything right now.
The bigger practical point is where the money lands. SJP’s intention is to reallocate it automatically to your other SJP funds. Only “some investors” will get money back into a transaction account. So the default is that your money stays invested with SJP, in a mix you didn’t choose for this purpose.
Will you get all your money back?
Not necessarily, and SJP says so plainly. Distributions “may be more or less” than you originally invested. What you get depends on when you bought in, how the fund performed, the price achieved for the private assets and the cost of selling the rest.
Three things work in investors’ favour:
- the hard-to-sell part has already been sold, so the remaining sale is bonds and cash
- SJP is paying the direct legal and administrative costs of the closure
- no fund charge is being taken during the wind-up
The unknown is the price. SJP hasn’t published what it got for the private market portfolio, or whether that was above or below the value the fund was carrying. Selling a whole portfolio in one go gives certainty, but buyers of private assets in bulk usually expect a discount. Your final payout will show whether there was one.
This is a market risk, not a firm failure. The Financial Services Compensation Scheme (FSCS) covers you if a regulated firm fails and owes you money, or in some cases for bad advice. It doesn’t cover a fall in the value of a fund. We covered how the FSCS works when an investment firm does fail in our guide to Jarvis Investment Management’s special administration.
Charges during the suspension
SJP has cut the fund charge to zero, and KKR has waived its fees for the rest of the fund’s life. That’s the cost inside the fund.
SJP clients usually pay more than one layer of charges, though. Depending on the product, there can be product or wrapper charges and an ongoing advice charge, worked out as a percentage of the value you hold. SJP’s announcement doesn’t say whether those other charges are paused on the frozen part of your holding.
Here’s what is at stake on an example holding. The percentages are for illustration only, so check your own charges on your SJP statement.
| Frozen holding | Ongoing charge (illustrative) | Cost per year | Cost for 3 months of suspension |
|---|---|---|---|
| £20,000 | 0.5% a year | £100 | £25 |
| £50,000 | 0.5% a year | £250 | £62.50 |
| £50,000 | 0.8% a year | £400 | £100 |
Small sums, but it’s a fair question: you’re paying for advice and management on money you can’t move.
Why the FCA’s new fund proposals matter here
Eight days after SJP’s suspension, the FCA published consultation paper CP26/35, “Fair redemption terms for authorised funds investing in illiquid assets”. It targets non-UCITS retail schemes that hold assets such as property and infrastructure, the same family of fund that the Diversified Assets fund belongs to.
| Today | Under the FCA’s proposals | |
|---|---|---|
| Access to your money | Some funds allow daily withdrawals with no notice | At least 90 days’ notice to redeem, longer if the assets need it |
| When stress hits | Fund may have to suspend all dealing | Notice period gives the manager time to sell in an orderly way |
| Cash buffers | Some funds hold extra cash to meet withdrawals | Less need for cash drag, more invested in the intended assets |
| Existing funds | No change | 2 years to comply, with at least 1 year’s notice to investors |
The consultation closes on 11 December 2026. Michelle Beck, the FCA’s director of markets, said funds “should be clear about whether they offer quick access or are built for longer-term investments like property.”
The FCA’s paper doesn’t name SJP. But the Diversified Assets fund shows the problem it describes: years of outflows from a fund that promised daily dealing while holding assets that couldn’t be sold daily. For investors, the lesson goes beyond SJP. If a fund holds private assets or property, check how quickly you can really get your money out, not just how often it deals.
Five questions to ask your SJP adviser
- Which of my products hold the fund, and how much is frozen in each? You may have it in an ISA, a bond and a pension at once.
- Where will my money be reinvested, and can I choose? The default is your other SJP funds. Ask whether you can pick the funds, or take cash, before the reallocation happens. The SJP client notice on the fund says details will follow after FCA approval.
- Are product and advice charges still being taken on the frozen amount? The fund charge is zero, but that may not be the whole bill.
- What price did the private assets sell for, compared with their last valuation? This is what decides whether your payout is close to the fund’s last published price.
- Are there tax consequences? For a direct holding, the wind-up is a disposal for capital gains tax. Inside a bond, ask whether anything counts as a chargeable event. ISAs and pensions shelter you from both.
If you think the fund was unsuitable for you in the first place, you can complain to SJP. If you’re unhappy with its final response, or it hasn’t replied within eight weeks, you can take it to the Financial Ombudsman Service.
Be wary of anyone who contacts you out of the blue offering to “unlock” frozen money or move it somewhere better. Suspended funds attract scammers. Deal only with your adviser or SJP’s admin centre on the number in your letter. If you’re also weighing up where to hold investments next year, our guide to the 2027 ISA transfer rules covers what changes for stocks and shares ISA holders. And if you hold cash with more than one bank in the same group, our explainer on Halifax moving to Lloyds shows how shared banking licences affect FSCS cover.
Verdict
SJP has handled the closure in a way that limits the damage. It sold the illiquid part first, cut the fund charge to zero, is paying the closure costs and expects to return money before the end of the year.
The open questions sit with investors. You won’t know your final payout until the sale proceeds are in. Unless you ask, your money will be reinvested in other SJP funds by default. And other charges may still be running on money you can’t touch. Ask your adviser the five questions above before the FCA decision arrives, so you’re ready to choose when SJP writes again.
FAQ
Why has the SJP Diversified Assets fund been suspended?
SJP says demand had fallen, with more money going out than coming in every year since 2023. Part of the fund was in private market assets that are slow to sell. After a review, SJP decided to close the fund and suspended dealing on 30 September 2026 while it applies to the FCA.
Can I sell or switch out of the fund now?
No. While the suspension lasts you can’t sell, switch or pay in. That includes SJP’s life and pension funds that invest fully in it.
When will I get my money?
After the FCA approves the closure, which SJP says usually takes about a month. The remaining holdings should then sell within days. SJP aims to return capital to clients in 2026.
Will I get back what I invested?
Not guaranteed. SJP says payouts may be more or less than you put in, depending on when you invested, performance and sale prices.
Will my money be paid out as cash?
For most investors, no. SJP plans to reinvest the proceeds automatically in your other SJP funds. Some investors will receive money into a transaction account. Ask your adviser what applies to you.
Am I paying charges while the fund is frozen?
The fund charge is now zero and KKR has waived its fees. SJP hasn’t said whether product or ongoing advice charges stop on the frozen amount, so check with your adviser.
Is my money protected by the FSCS?
The FSCS doesn’t cover falls in investment value. It protects you if an authorised firm fails and owes you money, and in some cases for bad advice. A fund wind-up like this is not a firm failure.
Sources: St. James’s Place announcement, 30 September 2026; SJP client notice; SJP planned closure timeline; FCA press release and CP26/35, 8 October 2026; fund size as reported by Money Marketing, 1 October 2026. This article is general information, not financial advice.


Recent Comments