

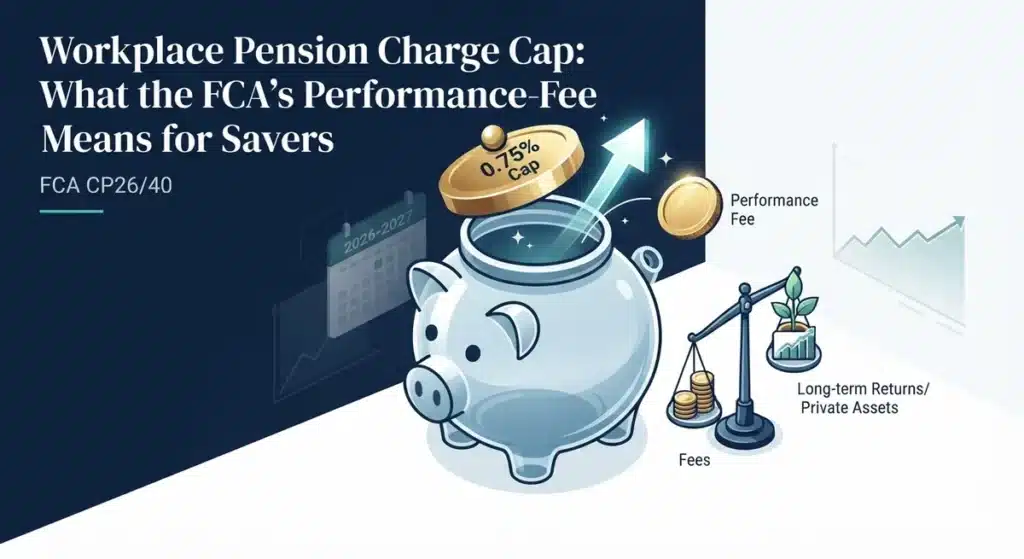
Almost every penny you pay into a workplace pension lands in a “default” fund you never chose. Since 2015, the charge on that fund has been capped at 0.75% a year. On 12 November 2026, the Financial Conduct Authority proposed the first real crack in that cap: a plan to let certain private-market performance fees sit outside it.
The regulator frames this as more choice for pension providers and better long-term returns for savers. It is also a change that could, for the first time in a decade, let some default-fund charges climb above 0.75%. Here is what the proposal actually says, what it would and would not change for your pot, and the questions worth asking before anyone celebrates.
Last updated: 13 November 2026
Table of Contents
Contents
- What the FCA is proposing
- The 0.75% charge cap, and why it is being loosened
- What a “performance fee” is in plain terms
- What changes for you as a saver
- The safeguards the FCA is attaching
- Where the risk sits
- Timeline: when any of this takes effect
- What to do now
- FAQ
What the FCA is proposing
The proposal lives in a consultation paper, CP26/40, published alongside a press release on 12 November 2026. In short, the FCA wants to exempt “specified performance-based fees” from the charge cap that applies to default funds in contract-based workplace pensions it regulates.
Contract-based schemes are the ones run under a contract between you and a provider such as an insurer or platform. They cover a large share of auto-enrolment savers. Trust-based schemes, overseen by The Pensions Regulator, already got this exemption in 2023. The FCA’s plan is to bring its own rulebook into line.
Three points define the proposal:
- It is permissive, not mandatory. Providers get the option to use the exemption. They are not required to, and the FCA says they should only do so where it is in savers’ interests.
- It targets private-market investments (private equity, venture capital and private credit), where performance fees are common and the cap currently acts as a barrier.
- It comes with conditions and safeguards, several of them lifted from the trust-based regime, plus a few the FCA has added after reviewing how private assets are valued.
The regulator is explicit on one line, repeated in both the press release and the paper: “greater flexibility is not a licence to charge more.” Any higher charge, it says, has to be justified by extra value delivered to savers.
The 0.75% charge cap, and why it is being loosened
The charge cap was introduced in 2015. It limits charges to 0.75% of funds under management in workplace default pension funds. The point was protection: employers pick the scheme, so employees have little say over the charges applied to their own savings, and the cap made sure everyone benefited from low costs.
It worked. According to the DWP’s Pension Provider Survey 2024-2025, which the FCA cites in CP26/40, median annual management charges now sit at 0.32% for multi-employer providers and 0.24% for single-employer trusts. That is less than half the cap.
So why change it? The FCA’s argument is that a cap built to drive down cost now blocks a different goal: value. Private-market assets usually carry performance fees, and a hard 0.75% ceiling makes providers nervous about holding them. Strong performance can trigger a bigger fee, which can push a fund over the cap and create a compliance headache. The safest route, for many schemes, has been to avoid private assets altogether.
This connects to a bigger policy push. In May 2025, the Mansion House Accord saw 17 major UK pension providers voluntarily commit to putting more money into private assets, including in the UK. Those providers named charge-cap alignment between trust-based and contract-based schemes as a “critical enabler” of that commitment. CP26/40 is, in part, the FCA delivering that alignment.
If you want the backdrop on the wider “productive finance” agenda the government is leaning on, our explainer on the DIGIT digital gilt covers how UK policy is trying to channel long-term money into domestic investment.
What a “performance fee” is in plain terms
Most funds charge a flat annual fee: a set percentage of what you have invested, paid whether the fund rises or falls. A performance fee is different. It is an extra slice the manager takes only when returns beat a pre-agreed level, known as a hurdle.
The classic structure in private markets is “2 and 20”: a 2% annual management fee, plus 20% of the gains above the hurdle. In pension-fund language that slice above the hurdle is often called carried interest. The FCA’s definition is deliberately broad, so it catches carried interest and similar profit-sharing even when it is not formally labelled a “performance fee”.
The table below sets out how the three fee ideas compare.
| Fee type | When it is charged | Counts toward the 0.75% cap today? | Under the proposal |
|---|---|---|---|
| Flat annual management charge | Every year, win or lose | Yes | No change, still capped |
| Transaction costs | When assets are bought or sold | Already exempt | No change |
| Performance fee / carried interest | Only when returns beat a set hurdle | Yes (counts toward the cap) | Could be exempt, if conditions are met |
The key shift is on that bottom row. Today a performance fee eats into the 0.75% headroom. Under the plan, a qualifying performance fee would sit outside the cap entirely.
What changes for you as a saver
Start with what does not change. The flat charge on your default fund is still capped at 0.75%. The proposal does not touch transaction-cost rules, your contributions, your tax relief or the state pension. If your provider never touches private assets, your pension may see no difference at all.
What could change is the ceiling on total cost for savers in funds that do start holding private assets with performance fees. In theory, a strong year in a private-equity holding could mean a performance fee that, added to the flat charge, takes the all-in cost above 0.75% for that period. The FCA’s bet is that this only happens when the fund has outperformed, so you are paying more because you earned more, net of the fee.
That is the crux of the debate. The upside is access. Supporters argue that private markets can improve diversification and lift net returns over the decades a pension is invested. The catch is that private assets are harder to value and harder to sell than shares and bonds, and a default-fund saver did not actively choose to hold them.
If you want to understand why the “hard to value, hard to exit” point matters, our coverage of the SJP Diversified Assets fund suspension shows what can happen when a fund holds assets that cannot be priced or sold quickly on demand.
Who this reaches first
Auto-enrolment savers in contract-based workplace schemes are the group in scope. If you are in a trust-based scheme, your regime already allows this. If you are in a self-invested personal pension picking your own funds, the default-fund charge cap does not apply to your choices in the same way.
The safeguards the FCA is attaching
CP26/40 is not a free pass. The exemption only applies where a set of protections is met, most mirrored from the trust-based rules and backed by the Consumer Duty. The main ones:
- Pre-agreed terms. Before investing, the provider and fund manager must agree how the performance fee is calculated and when it is paid. If a provider cannot get those terms in place, the fee stays subject to the cap.
- Look-through transparency. Providers must be able to see performance fees all the way down the chain, including in fund-of-funds structures where fees stack on fees.
- Fairness between savers. Schemes must consider how fees are allocated so that savers who join and leave at different times are treated fairly.
- Valuation due diligence. This is the FCA’s own addition, informed by its multi-firm review of how private assets are valued. If a provider cannot establish that a manager has proper valuation governance in place, it must not make the investment.
- Value-for-money oversight. Performance fees stay inside value-for-money assessments by Independent Governance Committees even when they are exempt from the cap.
The valuation safeguard is the one worth watching. A performance fee is calculated against a return, and in private markets that return is based on a valuation, not a live market price, until the asset is sold. Get the valuation wrong and the fee is wrong too.
Where the risk sits
The honest reading is that this trades a simple, predictable protection for a more complex one. The old rule was blunt but easy to check: 0.75%, full stop. The new approach relies on providers behaving well, on committees scrutinising fees, and on private-asset valuations being sound.
Three specific risks are worth naming:
- Cost creep without matching returns. The FCA’s safeguard is that higher charges must be justified by extra value. Justified by whom, and checked how often, will decide whether this holds in practice.
- Valuation uncertainty. Private assets are priced by models and judgement between buying and selling. A fee paid on an optimistic valuation is hard to claw back if the real exit price disappoints.
- Complexity for a default saver. The whole point of a default fund is that you do not have to engage. Layered private-market fees are the opposite of simple, which puts more weight on the governance you never see.
None of this makes the proposal wrong. Trust-based schemes have run under a similar exemption since 2023 without obvious disaster, and the FCA is adding protections rather than copying the old regime wholesale. But “it is in savers’ best interests” is doing a lot of work in this consultation, and that is exactly the phrase to test during the response period.
Timeline: when any of this takes effect
| Date | What happens |
|---|---|
| 12 November 2026 | FCA publishes CP26/40 and opens the consultation |
| 14 January 2027 | Deadline for responses |
| Summer 2027 | FCA expects to publish final rules, after reviewing feedback |
| H1 2027 | Separate Value for Money framework rules expected, which keep performance fees inside value-for-money checks |
Nothing is settled. These are proposals, open to change, and the earliest any final rule applies is after summer 2027. Anyone who wants to respond can do so through the FCA’s consultation page before 14 January.
What to do now
For most savers, the right answer is “nothing yet, but pay attention.” Still, a few steps are sensible:
- Find your current charge. Your annual pension statement or online dashboard shows the fund charge. Knowing whether you pay nearer 0.3% or nearer 0.75% tells you how much headroom exists.
- Check whether your fund mentions private assets. Fund factsheets list the asset mix. Most defaults are still heavily in listed shares and bonds.
- Watch your statements from 2027. If your provider adopts the exemption, the way charges are disclosed should change. Read the notes.
- Keep perspective. A pension is a decades-long investment. A fee change matters, but so does whether the fund actually delivers better net returns.
If you are weighing up moving part of your pot while this plays out, our guide to partial pension transfers explains which UK providers let you move only a portion rather than the whole pension. And if your provider starts offering more guidance around these changes, the new FCA targeted support regime is the framework that lets banks and pension firms nudge savers toward suitable options without full advice.
FAQ
Will my workplace pension charges go up?
Not automatically, and not yet. The flat charge on your default fund stays capped at 0.75%. Charges could rise above that only if your provider chooses to use the exemption and your fund starts holding private assets with performance fees. Even then, the FCA’s position is that any increase must be matched by extra value. The earliest final rules apply is after summer 2027.
What is the pension charge cap?
It is a limit, in place since 2015, that caps charges on default workplace pension funds at 0.75% of the money invested each year. It exists because employees do not choose their workplace scheme, so the cap protects them from high charges they cannot shop around for.
What is a performance fee?
An extra fee a fund manager takes only when returns beat an agreed level. The common private-market model is “2 and 20”: a 2% annual fee plus 20% of gains above a hurdle. It is different from the flat charge you pay every year regardless of performance.
Why does the FCA want to change the rule now?
Two reasons. The cap discourages providers from holding private-market assets, because performance fees can push a fund over the limit. And a 2025 industry agreement, the Mansion House Accord, named charge-cap alignment as a condition for 17 providers putting more money into private assets. CP26/40 aligns the FCA’s rules with the trust-based regime that already allows this.
What is happening to pensions in 2027?
On this specific change, the FCA expects final rules in summer 2027, with a separate Value for Money framework due in the first half of the year. Both are proposals or works in progress rather than confirmed rules, so the detail can still shift.
Does this affect my SIPP or personal pension?
The default-fund charge cap applies to workplace schemes, not to funds you actively pick yourself in a self-invested personal pension. If you choose your own investments, you are already outside the capped default world.
Are private assets riskier for my pension?
They carry different risks. Private equity, venture capital and private credit can improve diversification and long-term returns, but they are harder to value and harder to sell than listed shares and bonds. That is why the FCA has added a valuation due-diligence safeguard to the proposal.
Sources: FCA press release, “FCA proposes greater pension investment flexibility to support long-term value for savers” (12 November 2026); FCA Consultation Paper CP26/40, “Exempting performance fees from the workplace pensions charge cap” (12 November 2026); FCA consultation page for CP26/40; DWP Pension Provider Survey 2024-2025 (cited in CP26/40); Mansion House Accord (May 2025, cited in CP26/40).


Recent Comments