


TL;DR: Polly is a legitimate, FCA-regulated way for parents to arrange simple life cover, with an “Excellent” Trustpilot rating and policies underwritten by Swiss Re’s iptiQ. The catch: it sells its own single range of products rather than comparing the whole market, so it’s brilliant for ease but not the place to hunt down the cheapest possible premium. Get a Polly quote, then sanity-check it against a whole-of-market broker before you commit. 🟣 3.8 / 5
Disclosure: The Fintech Mag may earn a commission if you take out a policy through links on this page. It never changes our verdict, the facts we report or the price you pay.
You’ve probably seen Polly’s adverts — celebrity-fronted, aimed at mums, promising life cover “from £5 a month.” But what actually is Polly, who’s behind it, and is it any good? In this review we break down how Polly really works in 2026 (it has changed), who underwrites the policies, what it costs, what its thousands of Trustpilot reviewers say, and whether you’d be better off going direct.
The broader landscape of digital-first insurance distribution is reshaping how consumers access coverage, as exemplified by platforms offering streamlined quotes alongside developments in AI in insurance.
Table of Contents
What is Polly?
Polly (polly.co.uk) is a UK life-insurance brand aimed squarely at mums. It’s a trading name of Candid Insurance Services Ltd, a Bristol-based company that now operates under the wider CLARK UK banner, part of the German-founded CLARK group. Polly launched in 2015 and has become one of Britain’s more visible parent-focused insurance brands, largely on the back of celebrity- and influencer-led advertising featuring names such as Rebecca Adlington, Martine McCutcheon and Patsy Palmer.
Polly says “over 1 million customers” have come to it for advice since 2015. It’s worth knowing that Polly’s own small print defines that figure as customer enquiries since 2020 across both Polly and its partner brand TOM — so treat it as a marketing headline, not a verified count of policies placed. The brand, the regulation and the underwriting are all real; the round number is the part to take with a pinch of salt.
How does Polly work?
This is where a lot of older reviews are now out of date. Polly originally operated as a pure introducer — you’d submit an enquiry and your details were passed to a third-party broker. Since 2023, Polly distributes its own white-labelled policies, underwritten and manufactured by iptiQ, the digital insurer owned by reinsurance giant Swiss Re.
In practice there are two routes. You can complete Polly’s online Digital Pathway — a short health and lifestyle questionnaire that lets you apply entirely online, a route Polly added in early 2025. Or you submit your details and one of Polly’s in-house, FCA-regulated advisers calls you back to set up cover over the phone. The phone route is still the dominant experience reflected in Polly’s reviews.
The important nuance: Polly is not a whole-of-market broker. Its advisers recommend from Polly’s own iptiQ-backed range, not from every insurer on the market. That keeps things simple — but it means you’re not getting an independent comparison of competing insurers in the same conversation.
What does Polly offer?
Polly focuses on the protection products most relevant to parents:
Level term life insurance — a fixed payout over a set term.
Decreasing term life insurance — the payout reduces over time, often used alongside a repayment mortgage.
Critical illness / Serious Illness Cover (SIC) — a lump sum if you’re diagnosed with a covered serious condition.
Policies come with a bundled Square Health perk: 24/7 remote GP appointments for the family plus a set number of annual mental-health consultations, included in the premium. If you need something outside Polly’s niche, the same company runs sister brands for it: TOM (aimed at dads), Winston (over-50s guaranteed-acceptance whole-of-life cover for ages 50–80, no medical) and Anorak (income protection).
Is Polly legit and FCA-regulated?
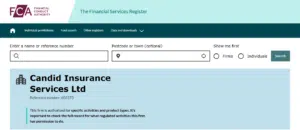
Yes. Polly is a trading name of Candid Insurance Services Ltd, which is authorised and regulated by the Financial Conduct Authority under reference number 603273 (company number 07279489, registered in Bristol). You can verify this yourself on the FCA Register at register.fca.org.uk — something worth doing with any insurer.
The underwriting adds reassurance: Polly’s life and serious-illness products are manufactured by iptiQ, a Swiss Re subsidiary. Policies underwritten by an FCA-regulated UK insurer of this kind are generally protected by the Financial Services Compensation Scheme (FSCS) — confirm the specifics in your own policy documents before relying on it.
Polly reviews and Trustpilot rating
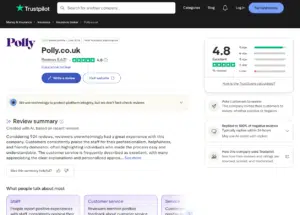
Polly is rated “Excellent” on Trustpilot, scoring around 4.8 out of 5 from more than 8,600 reviews as of mid-2026 — a genuinely strong score for the sector. (Trustpilot ratings move daily, so check the live figure when you read this.)
The positive reviews overwhelmingly name individual advisers and praise a calm, no-pressure, well-explained process — exactly what you’d hope for around an emotionally heavy purchase. The recurring criticism is the flip side of a phone-led model: a minority of reviewers say they were contacted by phone more often than they’d like after submitting an enquiry. If you’d rather avoid that, the online Digital Pathway is the route to use.
How much does Polly cost?
Polly advertises cover “from £5 a month.” Treat that as a marketing floor, not a quote: it’s the sort of premium a young, healthy non-smoker might pay for a modest amount of cover. Your actual price depends on your age, health, smoker status, the amount and length of cover, and whether you add critical illness.
Because Polly quotes from a single product range, the only way to know whether its price is competitive for you is to compare it. Get the Polly quote, then run the same details past a whole-of-market broker or a comparison site. If Polly comes back cheaper or similar and you value the simplicity and the Square Health extras, it’s an easy yes. If it’s noticeably pricier, you’ve lost nothing by checking.
Polly pros and cons
| ✅ Pros | ⚠️ Cons |
|---|---|
| FCA-regulated; policies underwritten by iptiQ (Swiss Re) | Not whole-of-market — one product range, one underwriter |
| Simple, jargon-light, built for busy parents | You can’t pick or compare insurers yourself |
| “Excellent” Trustpilot rating from thousands of reviews | Historically phone-led; some reviewers report frequent calls |
| You can now apply fully online (no phone call required) | Marketing-heavy — the “1 million customers” claim needs context |
| Included Square Health perk: remote GP & mental-health support | “From £5pm” is a headline, not a personalised quote |
Polly vs going direct: how it compares
Polly sits between a price-comparison site and a traditional broker. Here’s how the three routes stack up:
| Polly | Whole-of-market broker | Comparison site | |
|---|---|---|---|
| Compares multiple insurers | ❌ Own range only | ✅ | ✅ |
| Choose your insurer | ❌ | ✅ | ✅ |
| Advice included | ✅ (own products) | ✅ (independent) | ❌ Usually not |
| Apply fully online | ✅ Digital Pathway | Sometimes | ✅ |
| Underwriter | iptiQ (Swiss Re) | Varies | Varies |
| Best for | Ease & hand-holding | Complex needs / best fit | Cheapest headline price |
If you have a straightforward situation and want it sorted with minimal fuss, Polly’s model is appealing. If you have medical conditions, a high-risk job, or you simply want to be sure you’ve found the lowest price, an independent broker who can place you with any insurer is likely to serve you better.
Who is Polly best for?
Polly suits parents who want simple, guided life cover without trawling the market, who like the idea of a single, jargon-light provider, and who value the bundled remote-GP and mental-health support.
Look elsewhere if you want to compare every insurer and chase the cheapest premium, you have a complex health or occupation history that needs specialist placement, or you specifically want whole-of-market, independent advice.
The verdict
Polly does what it sets out to do well: it makes arranging family life cover simple, friendly and quick, it’s properly regulated, and its policies are underwritten by one of the biggest names in reinsurance. The honest limitation is that you’re buying from one shelf, not the whole shop — so the convenience can come at the cost of the keenest price or the best fit for an unusual situation. Used the smart way — as one quote you then compare — Polly earns its place. As your only quote, it’s a missed opportunity to check the rest of the market.
Polly life insurance FAQ
Is Polly life insurance legit?
Yes. Polly is a trading name of Candid Insurance Services Ltd, authorised and regulated by the FCA (reference 603273), with policies underwritten by Swiss Re’s iptiQ. You can confirm its status on the FCA Register at register.fca.org.uk.
Does Polly sell its own life insurance?
Yes — since 2023 Polly distributes its own white-labelled term life and serious illness products, underwritten by iptiQ. It is not a whole-of-market broker, so it recommends from its own range rather than comparing every insurer.
How much does Polly life insurance cost?
Polly advertises cover from £5 a month, but that’s an entry-level figure rather than a quote. Your premium depends on age, health, smoker status, cover amount and policy type. Compare it against a whole-of-market broker before buying.
What is Polly’s Trustpilot rating?
Around 4.8 out of 5, rated “Excellent,” from over 8,600 reviews as of mid-2026. Most reviews praise individual advisers; a minority mention frequent phone contact. The live score changes regularly.
Can I choose my own insurer with Polly?
No. Polly recommends its own iptiQ-underwritten products. For a choice of insurers, use a whole-of-market broker or a comparison site.
What are Polly’s sister brands?
TOM (for dads), Winston (over-50s whole-of-life cover) and Anorak (income protection) — all run by the same company, Candid Insurance Services Ltd, now trading as CLARK UK.
Not financial advice. This review is general information, not personal financial or insurance advice. Life insurance is a long-term commitment and the right choice depends on your circumstances — consider speaking to a regulated adviser before buying. Product details, prices, ratings and regulatory information were correct at the time of writing and can change; always check current details directly with the provider and on the FCA Register.
Sources: polly.co.uk (homepage, life-insurance, quote and footer regulatory statement); FCA Register (firm reference 603273); Trustpilot (Polly.co.uk profile, captured mid-2026); CLARK UK / clark.io company pages; iptiQ and Swiss Re (underwriting); Money to the Masses and Money People Online (independent Polly reviews); insurtech trade coverage of Polly’s iptiQ products and Digital Pathway launch.
Final Score: 3.8 / 5 🟣


Recent Comments